 Insights
The Token Cannot Have Its Own Reality: What the SEC’s New Stock Rules Reveal About Asset Identity
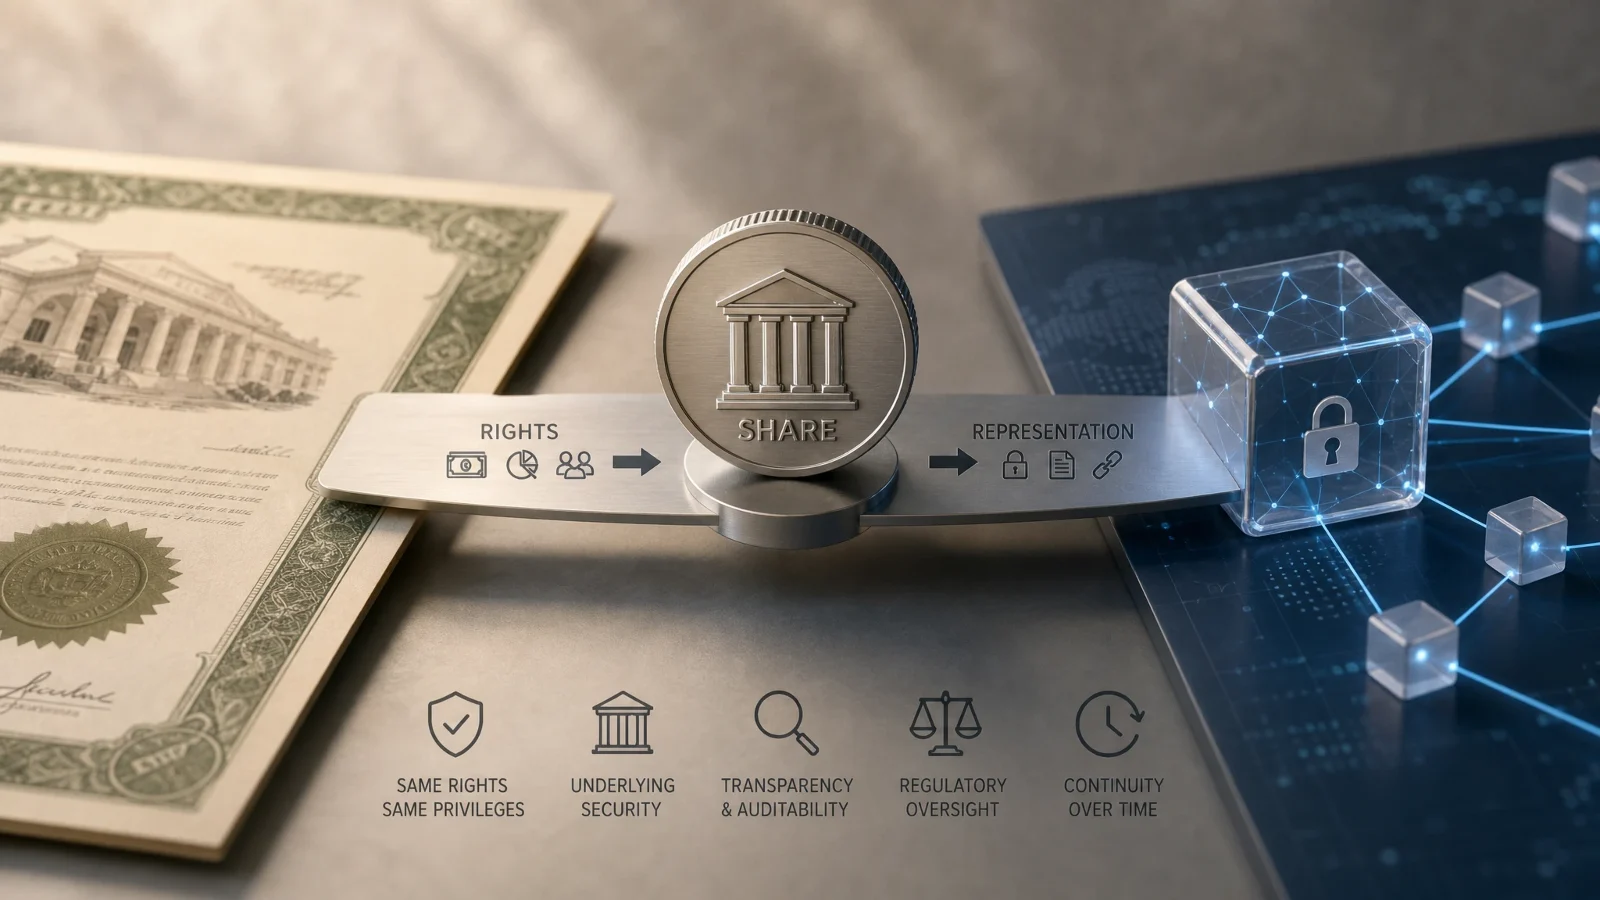
The US Securities and Exchange Commission has created a five-year conditional exemption allowing limited on-chain trading of tokenised NMS stocks on Tokenized Securities Venues. The conditions make the underlying infrastructure lesson unusually explicit: a tokenised stock must provide the same rights and privileges as the equivalent traditional share, issuers can object to unaffiliated third-party tokenisation, smart contracts must be public and auditable, and trading in the tokenised stock...
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
A stock can be represented on a blockchain.
That does not give the blockchain permission to invent a different stock.
This is the most important infrastructure lesson in the US Securities and Exchange Commission’s new Innovation Exemption.
On 17 September 2026, the SEC granted temporary, conditional relief allowing limited trading of tokenised National Market System stocks on new on-chain venues called Tokenized Securities Venues, or TSVs.
SEC: Innovation Exemption for tokenized NMS stock
The exemption is temporary.
It is conditional.
And its conditions are more interesting than the word token.
The SEC requires rights continuity
A TSV must verify that a tokenised NMS stock provides holders with the same rights and privileges as the equivalent traditional NMS stock.
The SEC explicitly refers to rights such as:
- dividends; and
- voting rights.
That means the tokenised representation cannot simply track the price of the share.
It must remain connected to the underlying shareholder-rights structure.
The key relationship is:
Underlying share
    ->
Tokenised representation
not:
Share price
    ->
Synthetic token
The token is a representation layer
The underlying security already has an identity.
It has:
- an issuer;
- a class;
- shareholder rights;
- an authoritative ownership process;
- a primary listing;
- corporate actions;
- trading status; and
- regulatory treatment.
Tokenisation adds another layer:
Issuer
    ->
Security
    ->
Authoritative rights
    ->
Token representation
    ->
On-chain venue
The representation must inherit from the security.
It should not become a parallel source of truth.
“Same rights” is more difficult than it sounds
Suppose the traditional share carries:
- voting rights;
- dividend rights;
- rights in a merger;
- tender-offer rights;
- rights in a split;
- rights in a spin-off;
- rights on liquidation; and
- information rights.
A tokenised version has to map those events into the digital environment.
The system therefore needs to answer:
Which exact share class does the token represent?
How does a token holder exercise voting rights?
How are dividends passed through?
What happens during a stock split?
What happens if the share is suspended?
A token balance is not enough.
The SEC explicitly rejects synthetic substitution
SEC Chairman Paul Atkins described the exemption as allowing tokenised stocks that are tokenised by or on behalf of the issuer, or by an unaffiliated third party, provided the instrument gives holders the same rights and privileges as the traditional security.
SEC Chairman Atkins: Innovation Exemption statement
The distinction is fundamental:
Tokenised security
is not automatically:
Synthetic exposure to security price
A synthetic instrument can be useful.
But it is a different asset.
The data model should say so.
Issuer objection creates an authority relationship
When an unaffiliated third party tokenises a stock, the TSV must provide written notice to the issuer and give the issuer an opportunity to object.
That adds another relationship:
Underlying issuer
    ->
Third-party tokenisation
    ->
Notice
    ->
Issuer objection / no objection
The issuer may not be the tokenisation provider.
But the issuer still matters.
That makes issuer status part of the tokenised asset record.
A digital representation cannot ignore the primary market state
One of the SEC’s clearest conditions is operational.
A TSV must stop trading a tokenised stock concurrently with a trading stoppage in the underlying NMS stock on the primary listing exchange.
That means:
Underlying trading state
    ->
Tokenised trading state
This is state synchronisation.
The tokenised venue cannot say:
Underlying stock halted
Token market continues normally
The digital representation inherits the market event.
“Representation inherits state” is the key rule
This principle goes beyond trading halts.
A serious tokenised-security architecture should be ready for:
Stock split
Dividend
Merger
Tender offer
Spin-off
Delisting
Suspension
Name change
Ticker change
Rights issue
Record date
Voting event
Each event originates in the underlying security.
The representation has to absorb the consequences.
That is a different problem from minting a token.
Corporate actions need event propagation
Suppose an issuer announces a 2-for-1 stock split.
The underlying security changes.
The tokenised representation needs a corresponding state transition.
A possible lifecycle is:
Issuer corporate action
    ->
Authoritative security record updated
    ->
Entitlement calculated
    ->
Token representation adjusted
    ->
Venue balances reconciled
If any layer fails to update, the digital representation can diverge from the asset.
Dividends expose the rights chain
A shareholder may be entitled to a dividend based on a record date.
For a tokenised stock, the infrastructure may need to connect:
Issuer
    ->
Dividend declaration
    ->
Record date
    ->
Authoritative shareholder entitlement
    ->
Token holder mapping
    ->
Distribution
A wallet balance observed after the record date may not, by itself, prove who had the entitlement at the relevant time.
The history matters.
Voting exposes the same problem
The SEC specifically requires the same rights and privileges, including voting rights.
That creates questions such as:
- who receives the proxy material;
- how a token holder submits instructions;
- which record date controls;
- how beneficial ownership is mapped;
- whether intermediaries aggregate votes;
- how duplicate voting is prevented; and
- which system is authoritative.
Again:
Token holder
is not enough.
The rights workflow matters.
Ownership and possession can diverge
A token may sit in a wallet.
That wallet state may represent an entitlement.
But securities markets can contain multiple ownership concepts:
- registered owner;
- beneficial owner;
- custodian;
- broker;
- nominee;
- depository position;
- token holder; and
- economic beneficiary.
A durable asset model needs to preserve the actual structure.
It should not collapse all of them into:
Owner
Transfer agents remain important
Earlier in September 2026, the SEC separately proposed modernising its transfer-agent rules to reflect electronic and blockchain-based recordkeeping and uncertificated securities.
That is relevant context.
Tokenisation does not eliminate the function of authoritative ownership recordkeeping.
It changes how that function can be implemented.
SEC: Proposed Transfer Agent Rule Modernization
A blockchain can participate in the recordkeeping architecture.
It does not automatically become the legally authoritative register.
The smart contract itself becomes infrastructure evidence
The SEC requires smart contracts used by a TSV to be:
- auditable;
- public; and
- deployed on a public, permissionless distributed ledger.
That creates an unusual source of operational evidence.
An institutional asset record may need to connect:
Security
    ->
Token contract
    ->
Contract version
    ->
Audit
    ->
Deployment
    ->
Venue use
The code becomes part of the provenance chain.
Public code does not mean simple rights
Even if the smart contract is visible, legal rights may still depend on:
- offering terms;
- venue rules;
- transfer-agent records;
- custody arrangements;
- issuer actions;
- investor eligibility;
- securities law;
- corporate law; and
- contractual arrangements.
Code transparency is useful.
It does not eliminate legal interpretation.
Venue state is another separate object
The SEC exemption applies to Tokenized Securities Venues using permissioned automated market makers and liquidity pools.
That means the same tokenised stock can have:
- underlying security state;
- token state;
- holder state;
- venue state;
- liquidity-pool state; and
- settlement state.
Those layers need to stay coordinated.
Permissioned access matters
A public blockchain does not necessarily imply permissionless securities trading.
The SEC framework requires TSVs to set access standards for participants.
The structure can therefore be:
Public blockchain
+
Public smart contract
+
Permissioned participant access
This distinction is easy to lose in generic blockchain descriptions.
The network and the market-access regime are different properties.
Trading limits create another market-state field
The SEC exemption imposes limits on the number of symbols and trading volume.
That means a tokenised security can be technically available on a venue while regulatory conditions constrain how much activity may occur.
A structured venue record could include:
- permitted symbol;
- volume cap;
- access status;
- suspension;
- underlying halt;
- venue notice;
- current liquidity pool;
- reporting state; and
- exemption eligibility.
Settlement is not just a blockchain transaction
A token transfer can be technically final on a distributed ledger.
The broader securities transaction may still depend on:
- payment;
- legal settlement rules;
- participant obligations;
- recordkeeping;
- reconciliation;
- corporate-action entitlement;
- custody;
- regulatory reporting; and
- error handling.
The token transaction is one settlement event.
It may not be the whole legal settlement story.
Tokenisation creates a reconciliation obligation
When a security has both traditional and tokenised forms, the system needs to prevent divergence.
Relevant reconciliations may include:
Token supply
vs
Underlying authorised position
Token holder records
vs
Authoritative ownership records
Corporate-action entitlement
vs
Token distribution
Trading status
vs
Primary-exchange status
The value of the representation depends on this continuity.
A tokenised security needs two histories
The underlying security has its own lifecycle.
The token representation has another.
For example:
Underlying:
Issue
-> Trade
-> Dividend
-> Split
-> Halt
-> Resume
-> Merger
while the token may have:
Mint
-> Transfer
-> Lock
-> Burn
-> Remint
The histories need to connect.
A single event log is not enough.
The primary security identifier should remain visible
A token contract address is useful.
It should not replace the underlying security identifier.
A structured record may need:
Issuer
Security class
CUSIP / ISIN / other authoritative identifier
Exchange / listing
Token contract
Network
Token symbol
Venue
The token identifier tells us which representation is being used.
The security identifier tells us what is being represented.
Corporate-action mismatch is a material risk
Suppose the underlying share is subject to a tender offer.
A token holder may need to choose whether to participate.
If the token system cannot pass that right through, the representation is no longer economically equivalent.
Likewise, if the underlying share is delisted but the token continues to appear as a normally trading asset, the digital state has broken away from reality.
The infrastructure should detect these mismatches.
Issuer consent and token lifecycle need history
An issuer may:
- receive notice;
- not object;
- later raise concerns;
- change corporate structure;
- merge;
- delist; or
- cease to exist.
The token record should therefore preserve issuer-related events over time.
A single boolean such as:
Issuer approved: Yes
may be misleading.
The exact SEC framework is based on notice and opportunity to object for relevant third-party tokenisations.
The data model should preserve what actually happened.
A tokenised-security Asset Passport should connect the layers
Underlying security
- issuer;
- legal entity identifier;
- security class;
- authoritative identifier;
- primary listing exchange;
- ticker;
- voting rights;
- dividend rights;
- other shareholder rights;
- current trading status; and
- corporate-action history.
Authoritative ownership
- transfer agent;
- depository;
- registered owner;
- beneficial-owner structure;
- custody chain;
- record date;
- position source;
- reconciliation date; and
- current authoritative state.
Token representation
- token issuer;
- issuer relationship;
- token contract;
- network;
- contract version;
- deployment address;
- token symbol;
- token supply;
- minting rules;
- burning rules;
- transfer restrictions; and
- current token state.
Rights mapping
- underlying right;
- token-holder equivalent right;
- dividend mechanism;
- voting mechanism;
- corporate-action mechanism;
- redemption or conversion;
- settlement mechanism;
- exceptions; and
- evidence.
Issuer notice
- tokenisation provider;
- unaffiliated-party status;
- notice date;
- notice recipient;
- objection period;
- issuer response;
- objection;
- effective status; and
- source.
Venue
- TSV;
- access rules;
- permissioned participants;
- AMM or liquidity pool;
- symbol limit;
- volume limit;
- trading state;
- halt state;
- public notice;
- transaction-data reporting; and
- exemption status.
State synchronisation
- underlying halt;
- token halt;
- halt timestamp;
- resume timestamp;
- corporate action;
- token adjustment;
- reconciliation;
- exception;
- unresolved mismatch; and
- reviewer.
Provenance
- issuer filing;
- exchange notice;
- transfer-agent record;
- SEC order;
- venue disclosure;
- smart-contract source;
- smart-contract audit;
- blockchain transaction;
- reconciliation report;
- timestamp;
- version; and
- reviewer.
A mismatch should be a first-class state
A good system should be able to say:
Underlying state: Halted
Token state: Trading
Mismatch: Critical
or:
Dividend entitlement: Declared
Token pass-through: Pending
or:
Issuer notice: Sent
Objection period: Open
The system should not hide operational disagreement behind a green status icon.
AI can monitor synchronisation but should not invent shareholder rights
AI can help:
- extract corporate actions;
- map issuer filings to token contracts;
- detect trading-halt mismatches;
- compare token supply with authoritative positions;
- identify dividend dates;
- compare shareholder-right descriptions;
- classify transfer restrictions;
- flag stale issuer notices;
- monitor smart-contract version changes; and
- create a timeline of underlying and token events.
AI should not independently decide:
- that a token provides legally equivalent shareholder rights;
- who is the legal owner;
- whether an issuer has validly objected;
- whether a transfer is legally final;
- whether a venue satisfies the exemption;
- whether a corporate action was correctly implemented;
- whether a smart contract is legally enforceable; or
- whether a token is suitable for an investor.
Those require authoritative records, legal analysis and regulated market processes.
What DaDepo can contribute
DaDepo does not need to operate a tokenised exchange.
The useful role is to preserve continuity between the asset and its representation.
A security Asset Passport can connect:
Issuer
    ->
Underlying security
    ->
Authoritative rights
    ->
Ownership record
    ->
Token representation
    ->
Venue
    ->
Trading state
    ->
Settlement
    ->
Corporate actions
That makes it easier to ask:
- what exact security is represented;
- what rights the token is supposed to preserve;
- where authoritative ownership is recorded;
- who created the token;
- whether the issuer was notified;
- whether the token is currently tradeable;
- whether the underlying stock is halted;
- whether a corporate action has propagated; and
- which evidence supports each state.
The Asset Passport should not replace the market infrastructure.
It should make the relationships visible.
What DaDepo does—and does not do
Creating or reviewing a tokenised-security Asset Passport does not mean that DaDepo has:
- issued stock;
- tokenised a security;
- acted as transfer agent;
- maintained the shareholder register;
- acted as depository;
- provided custody;
- operated a TSV or exchange;
- provided a liquidity pool;
- acted as broker or dealer;
- verified regulatory exemption eligibility;
- determined shareholder rights;
- processed corporate actions;
- settled a securities transaction;
- determined settlement finality;
- guaranteed token-to-security reconciliation;
- provided investment advice; or
- provided legal, regulatory, tax, accounting, brokerage, custody, clearing, settlement or valuation advice.
Important: DaDepo provides technology and information tools. It does not provide securities issuance, tokenisation, transfer agency, depository, custody, exchange, brokerage, dealing, clearing, settlement, legal, regulatory, tax, accounting, investment or valuation advice or services unless a specific service is expressly identified and lawfully provided. Security ownership, shareholder rights, token equivalence, issuer rights, settlement and regulatory treatment depend on authoritative market infrastructure, governing documents, applicable law and qualified professional review.
A practical tokenised-security checklist
- Underlying security: Which exact traditional security is represented?
- Issuer: Which legal entity issued it?
- Class: Which share class or security class applies?
- Identifier: Which authoritative identifier anchors the asset?
- Primary market: Where is the underlying security listed or recorded?
- Rights: Which dividends, voting and other rights attach to it?
- Ownership: Where is authoritative ownership recorded?
- Token issuer: Who created the representation?
- Token contract: Which smart contract defines it?
- Network: On which ledger is it deployed?
- Rights equivalence: How are underlying rights passed to token holders?
- Issuer notice: Was the issuer notified where required?
- Issuer objection: Is any objection active?
- Supply: How is token supply reconciled with the underlying position?
- Transfer: What legal effect does an on-chain transfer have?
- Access: Who is permitted to trade?
- Venue: Which TSV or other venue is used?
- Trading status: Is the underlying stock trading?
- Token trading status: Is the tokenised representation trading?
- Halt synchronisation: Do the two states match?
- Corporate actions: How are splits, dividends and mergers propagated?
- Record dates: Which system determines entitlement?
- Voting: How are voting instructions transmitted?
- Settlement: Which events establish completion?
- Reconciliation: When were token and authoritative records last compared?
- Smart-contract audit: Which audit exists and which version did it cover?
- Regulatory basis: Which exemption, registration or rule applies?
- Provenance: Can every right and state be traced to a source and timestamp?
If the answer to “does this token still represent the same rights and current state as the underlying security?” is unclear, the tokenised asset record is incomplete.
The broader lesson goes beyond equities
The same continuity problem appears in:
- tokenised bonds;
- tokenised funds;
- tokenised money-market instruments;
- tokenised private credit;
- tokenised receivables;
- tokenised commodities; and
- other digitally represented real-world assets.
The representation can use a new rail.
The asset still has an authoritative identity and rights structure.
The token cannot have its own reality
The SEC’s exemption is important because it turns that idea into operating conditions.
The tokenised share must preserve the underlying rights.
The issuer can matter even when a third party creates the representation.
The smart contract must be inspectable.
The tokenised venue must react when the underlying stock stops trading.
The digital market therefore cannot simply detach from the security it represents.
A representation is trustworthy only while it remains synchronised with the asset’s authoritative rights and state.
The token can have a new rail.
It cannot have its own reality.
Further reading
- SEC: Innovation Exemption for tokenized NMS stock
- SEC Chairman Atkins: Innovation Exemption statement
- SEC Commissioner Uyeda: Statement on the Innovation Exemption
- SEC: Order and request for comment, File No. 4-927
- Reuters: US securities regulator rolls out five-year exemption for tokenized stock trading
- SEC: Crypto@SEC — transfer-agent and tokenisation developments