 Insights
Institutional Capital Does Not Buy Projects: Why Private Assets Need to Become Portable Before They Become Investable
The World Bank Group says it mobilised a record $112 billion of private capital in FY2026 and wants to exceed $200 billion within two to three years. The strategic shift is not simply to originate more projects. It is to standardise and package loans into structures that pension funds, insurers and asset managers can hold. IFC’s Emerging Markets Securitization Program shows the model in practice: two CLO transactions have issued more than $1 billion of securities backed by 119 IFC-originated...
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
Large institutional investors have enormous pools of capital.
That does not mean they want to underwrite thousands of individual private loans one by one.
That difference is becoming central to development finance.
On 17 September 2026, the World Bank Group said it had mobilised a record $112 billion of private capital in FY2026.
The figure had been $35 billion in FY2022.
World Bank: Record private capital mobilisation for developing countries
Reuters reported that World Bank President Ajay Banga wants to lift annual private-capital mobilisation to more than $200 billion within two to three years.
The important part is how.
The World Bank is working to standardise and package loans so that pension funds, insurers and asset managers can invest at scale.
Banga’s explanation was unusually direct:
Large pools of institutional money do not typically come for individual projects.
Reuters: World Bank boosts private capital mobilisation to record $112 billion
That creates a useful private-market principle:
An asset must become portable before a portfolio can become scalable.
A project is not yet an asset class
A development project can be investable on its own.
It may have:
- a borrower;
- a loan agreement;
- collateral;
- financial statements;
- covenants;
- repayment history;
- environmental and social documentation;
- insurance;
- guarantees; and
- a credit assessment.
But institutional investors often need something else.
They need repeatability.
They need to compare one exposure with another.
They need eligibility rules.
They need portfolio data.
They need standard reporting.
They need a structure they already know how to hold.
That is the difference between:
Good project
and:
Investable asset class
IFC is already testing the model in live transactions
The World Bank Group’s private-sector arm, IFC, has created the Emerging Markets Securitization Program, or EMSP.
The programme packages IFC-originated loans into tradable securities.
IFC says that two transactions have now issued more than $1 billion.
The combined portfolios contain 119 IFC-originated loans across industries and regions.
IFC: Emerging Markets Securitization Program
That creates a visible chain:
Individual borrower
    ->
Private loan
    ->
Standardised portfolio data
    ->
Eligible pool
    ->
CLO
    ->
Rated tranche
    ->
Institutional investor
The underlying loan does not disappear when the CLO is issued.
It becomes one component of a larger investment structure.
The second transaction makes the model concrete
IFC closed its second EMSP transaction in June 2026.
The $509 million CLO packaged 62 IFC-originated loans.
Its structure included:
- $320 million Aaa-rated senior tranche;
- $50 million Aa1-rated tranche;
- $80 million mezzanine tranche insured by a consortium of credit insurers; and
- $59 million equity tranche held jointly by IFC and the UK Foreign, Commonwealth & Development Office.
Participating investors included:
- PIMCO;
- L&G;
- Shizuoka Bank;
- Sona Asset Management; and
- other institutional investors.
IFC: Second Emerging Markets CLO
The structure matters because investors do not need to become the bilateral lender to every underlying borrower.
They receive exposure through a familiar portfolio instrument.
Standardisation is not homogenisation
A common mistake is to think:
Standardised
means:
Identical
It does not.
The 119 underlying loans can differ by:
- country;
- borrower;
- sector;
- currency;
- tenor;
- interest rate;
- collateral;
- covenant package;
- risk;
- repayment profile;
- guarantee;
- legal framework; and
- servicing history.
Standardisation means those differences can be represented consistently.
The objective is not to erase heterogeneity.
It is to make heterogeneity comparable.
The underlying asset still needs its own identity
Suppose a portfolio contains 119 loans.
A portfolio-level record such as:
EMSP portfolio
is useful.
It is not enough.
For every loan, the system may still need:
- borrower;
- facility identifier;
- origination date;
- original amount;
- current principal;
- currency;
- maturity;
- interest terms;
- payment schedule;
- collateral;
- guarantee;
- covenant status;
- arrears;
- restructuring history;
- transfer status;
- portfolio membership; and
- source evidence.
The portfolio cannot substitute for the loan record.
A portfolio is another asset layer
Once loans are pooled, a new asset relationship appears.
The system now needs to represent:
Loan A
Loan B
Loan C
...
    ->
Portfolio
    ->
SPV
    ->
Tranche
    ->
Investor
Each layer has its own lifecycle.
A borrower may prepay.
A loan may default.
A loan may be substituted.
A tranche may amortise.
A rating may change.
An investor may sell its note.
The asset infrastructure must preserve these events without confusing the layers.
Portfolio membership is a state, not a label
A loan can move through portfolio states such as:
Candidate
    ->
Eligible
    ->
Selected
    ->
Transferred
    ->
Active in portfolio
Later:
Active
    ->
Prepaid
or:
Active
    ->
Defaulted
or:
Active
    ->
Substituted / removed
A field called:
Portfolio: EMSP II
does not preserve that history.
The system needs the event that created or ended portfolio membership.
Eligibility needs evidence
Before a loan enters a portfolio, it may need to satisfy defined rules.
Possible eligibility criteria can concern:
- jurisdiction;
- borrower type;
- sector;
- credit quality;
- arrears;
- maturity;
- currency;
- documentation;
- concentration;
- transferability;
- sanctions;
- environmental criteria;
- collateral;
- guarantee status; and
- other transaction-specific conditions.
The exact EMSP eligibility rules should be read from the governing documents.
The general infrastructure principle is:
Eligible
should resolve into:
Eligibility rule
+
Current asset field
+
As-of date
+
Source
+
Reviewer
Eligibility can change after closing
A loan can be eligible when transferred and later deteriorate.
The borrower can miss a payment.
A covenant can be breached.
A guarantee can expire.
Collateral value can change.
The borrower can restructure.
The loan still exists.
Its portfolio state may change.
That means eligibility and performance need time-aware records.
Current balance matters more than original amount
A loan may have been originated at:
$20 million
Years later its current balance may be:
$12.4 million
A portfolio record must distinguish:
- original commitment;
- amount drawn;
- principal outstanding;
- accrued interest;
- overdue amount;
- undrawn commitment;
- repayments;
- prepayments; and
- write-offs.
The original contract amount is not the current asset exposure.
The loan and the security are different objects
A secured private loan may connect to:
Loan
    ->
Security agreement
    ->
Collateral asset
The collateral can have its own:
- identity;
- owner;
- location;
- valuation;
- priority;
- encumbrance;
- insurance;
- release history; and
- enforcement state.
Pooling the loan into a CLO does not collapse those objects.
The portfolio needs to preserve them.
Guarantees are another layer
Development-finance loans may also have:
- sponsor guarantees;
- parent guarantees;
- political-risk protection;
- multilateral support;
- insurance; or
- other risk-sharing arrangements.
Those rights can materially affect investor exposure.
A field such as:
Guaranteed: Yes
is too shallow.
The record should ask:
Who guarantees what?
For how long?
Under which conditions?
Has the guarantee been called?
Originate-to-distribute changes the lender lifecycle
Traditional bilateral lending can look like:
Originate
    ->
Hold
    ->
Collect
    ->
Maturity
An originate-to-distribute model adds:
Originate
    ->
Season / monitor
    ->
Standardise
    ->
Select
    ->
Transfer or participate
    ->
Pool
    ->
Issue securities
    ->
Continue servicing / monitoring
That is a different information problem.
The asset has to remain understandable after it leaves its original bilateral context.
Transferability cannot be assumed
A loan can be economically attractive and still difficult to transfer.
Transfer may depend on:
- borrower consent;
- lender consent;
- assignment clauses;
- participation mechanics;
- local law;
- regulatory restrictions;
- tax;
- confidentiality;
- security transfer;
- registration;
- sanctions; and
- notice.
A standardised asset record should include transferability as a sourced state.
Not as an assumption.
“Portable” means more than legally transferable
Legal transferability is only one part.
Operational portability also matters.
A loan is easier to package when another institution can understand it without reconstructing the entire origination file.
That requires:
Identity
Terms
Balance
Performance
Security
Covenants
Valuation
Transfer restrictions
Evidence
Current state
Portability is partly a legal property.
It is also an information property.
Institutional investors need comparable data
A pension fund or insurer evaluating a diversified portfolio may need to compare exposures across:
- sectors;
- geographies;
- currencies;
- maturities;
- ratings;
- internal credit grades;
- collateral;
- concentration;
- performance;
- environmental risk; and
- expected cash flows.
That is hard if every underlying loan is represented by a bespoke PDF folder.
It becomes easier if each loan has a structured, source-backed record.
The wrapper should not hide the assets
A CLO gives institutional investors a familiar security.
That is useful.
It can also create abstraction.
The investor may own a note rather than the underlying loans.
But the quality of the note still depends on the underlying portfolio.
A robust system therefore needs both:
Security-level record
and:
Underlying asset-level records
The wrapper improves access.
It should not destroy transparency.
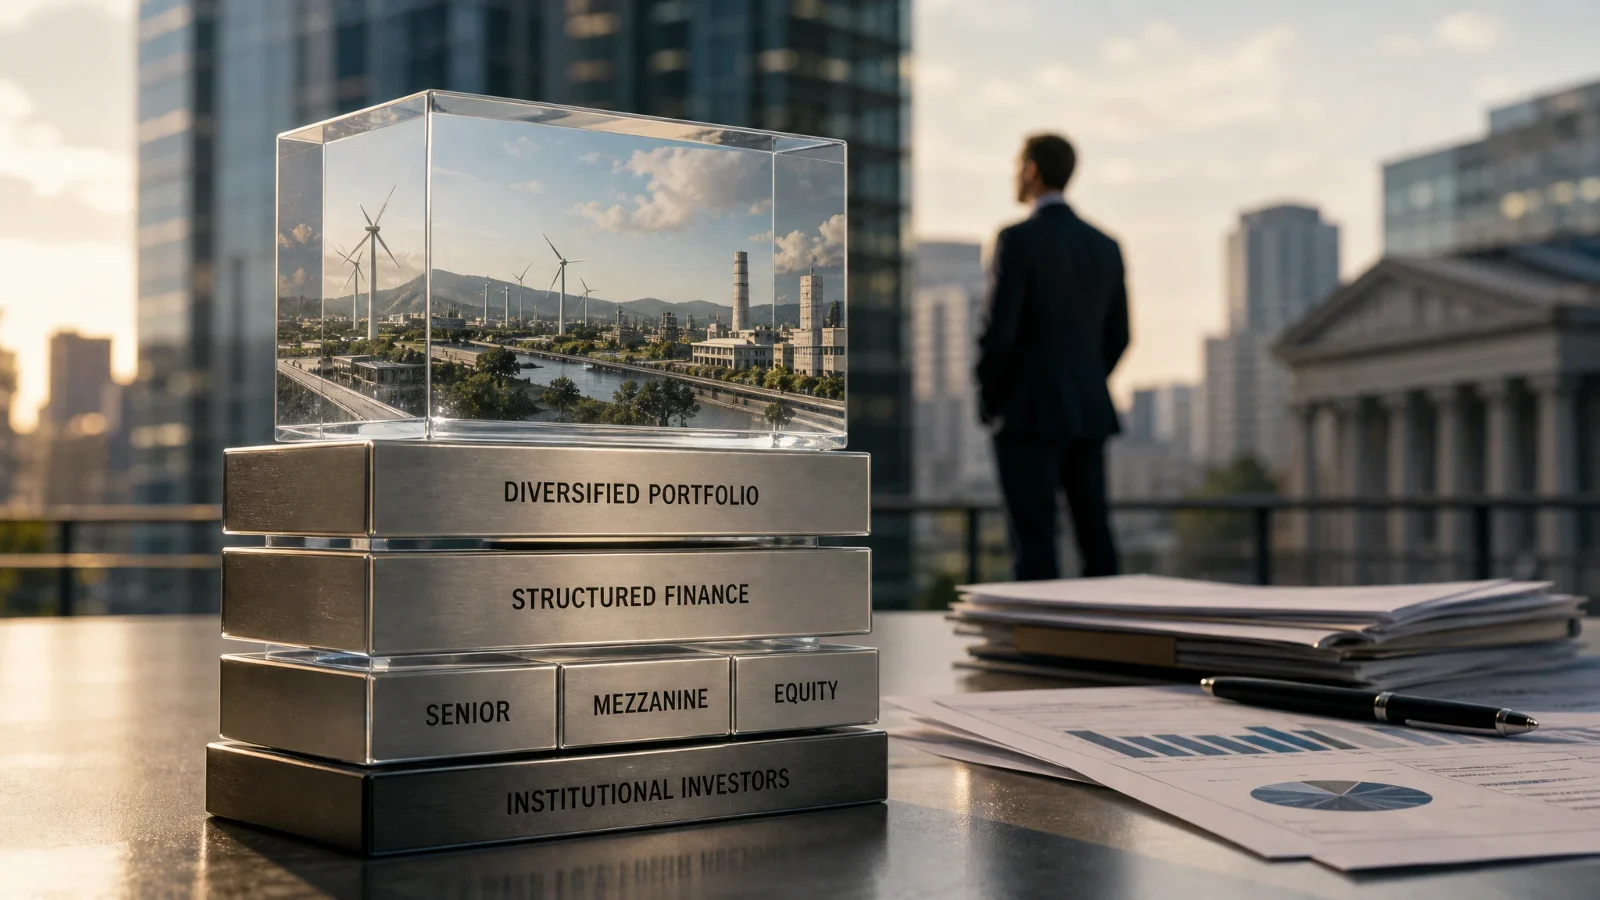
Tranching creates a new rights map
In a CLO, different investors can have different rights over the same pool.
The structure may contain:
Senior tranche
Mezzanine tranche
Equity tranche
Those positions differ in:
- priority;
- coupon;
- expected loss;
- cash-flow entitlement;
- voting rights;
- control rights;
- maturity;
- rating; and
- sensitivity to portfolio performance.
The underlying portfolio is shared.
The investor rights are not.
Credit insurance adds another risk-transfer layer
In the second EMSP transaction, the mezzanine tranche was insured by a consortium of credit insurers.
That means the structure contains another chain:
Underlying loans
    ->
Portfolio credit risk
    ->
Mezzanine tranche
    ->
Insurance protection
The insurance is not the loan.
It is not the tranche.
It is a risk-transfer contract around the tranche.
Again, the graph matters.
Capital recycling depends on asset continuity
IFC says the programme allows it to recycle capital into new lending.
The logic is:
Originate loans
    ->
Package exposure
    ->
Bring in institutional capital
    ->
Release or recycle capital
    ->
Originate more loans
For that model to scale, the assets must survive the transition from origination system to capital-markets structure.
Identity continuity becomes operational infrastructure.
Repeat issuance increases the value of consistent schemas
A one-off transaction can be assembled manually.
A repeat programme creates a different problem.
After several issuances, the manager needs to answer:
Which assets belong to which vintage?
Were definitions consistent?
Did the same borrower appear in several pools?
Which assets prepaid?
Which eligibility rules changed?
Can performance be compared across vintages?
A reusable asset schema becomes more valuable with every transaction.
Data lineage matters during securitisation
An investor-visible field might originate from:
Borrower document
    ->
IFC system
    ->
Portfolio dataset
    ->
Transaction report
    ->
Investor disclosure
If a number changes, the institution needs to know why.
A source-backed model can preserve:
- original source;
- extraction date;
- transformation;
- reviewer;
- effective date;
- portfolio snapshot; and
- later correction.
That is essential for trust.
A debt-portfolio Asset Passport should preserve both levels
Underlying loan identity
- borrower;
- borrower identifier;
- facility identifier;
- lender;
- origination date;
- currency;
- original commitment;
- current principal;
- maturity;
- interest terms;
- payment schedule; and
- governing law.
Performance
- scheduled payment;
- amount paid;
- days past due;
- arrears;
- default state;
- restructuring;
- waiver;
- covenant breach;
- watchlist state;
- internal credit grade;
- effective date; and
- source.
Security and support
- collateral;
- collateral identifier;
- security type;
- priority;
- valuation;
- valuation date;
- guarantor;
- guarantee amount;
- insurance;
- risk-sharing arrangement; and
- enforcement state.
Transferability
- assignment permitted;
- participation permitted;
- consent required;
- notice required;
- confidentiality restriction;
- jurisdictional restriction;
- tax issue;
- security-transfer mechanics;
- transfer event; and
- current holder.
Portfolio membership
- candidate date;
- eligibility assessment;
- eligibility result;
- selection date;
- transfer date;
- pool identifier;
- portfolio vintage;
- substitution;
- removal;
- prepayment;
- default; and
- current membership state.
Portfolio
- portfolio identifier;
- closing date;
- asset count;
- aggregate balance;
- geography;
- sector;
- currency;
- concentration;
- weighted maturity;
- performance metrics;
- eligibility rules; and
- reporting date.
Securitisation
- SPV;
- transaction;
- tranche;
- principal;
- rating;
- coupon;
- priority;
- investor;
- insurance;
- listing venue;
- payment waterfall; and
- current security state.
Provenance
- loan agreement;
- amendment;
- borrower financials;
- collateral document;
- valuation;
- payment record;
- eligibility test;
- transfer document;
- portfolio tape;
- investor report;
- rating document;
- effective date;
- version; and
- reviewer.
AI can standardise data but should not invent eligibility
AI can help:
- extract loan terms;
- normalise borrower names;
- map collateral;
- identify maturity dates;
- compare covenant language;
- detect missing fields;
- reconcile balances;
- classify amendments;
- build portfolio tapes;
- find duplicate borrower exposures;
- detect inconsistent currencies or units; and
- trace changes between reporting periods.
AI should not independently decide:
- whether a loan is legally transferable;
- whether security is perfected;
- whether a borrower is creditworthy;
- whether an asset satisfies transaction eligibility;
- whether a rating is appropriate;
- whether a guarantee is enforceable;
- whether a transfer is a true sale;
- whether a portfolio is suitable for an investor; or
- how a security should be priced.
Those require authoritative documents, transaction rules and professional judgment.
What DaDepo can contribute
DaDepo does not need to become a CLO manager or development bank.
The useful role is upstream.
It can help make private assets easier to inspect, compare and package before they reach capital-markets infrastructure.
A structured path could be:
Loan
    ->
Asset Passport
    ->
Comparable asset data
    ->
Eligibility
    ->
Portfolio
    ->
Transfer
    ->
Securitisation
    ->
Institutional investor
The Asset Passport does not create the securitisation.
It can reduce the information friction before it.
What DaDepo does—and does not do
Creating or reviewing a loan or debt-portfolio Asset Passport does not mean that DaDepo has:
- originated a loan;
- underwritten a borrower;
- made a credit decision;
- determined a loan is transferable;
- obtained borrower consent;
- perfected security;
- determined portfolio eligibility;
- structured a CLO;
- created an SPV;
- assigned a rating;
- arranged a securities offering;
- provided credit insurance;
- acted as trustee;
- acted as asset manager;
- provided brokerage;
- priced a security;
- recommended an investment; or
- provided legal, regulatory, tax, accounting, investment or valuation advice.
Important: DaDepo provides technology and information tools. It does not provide lending, underwriting, securitisation, ratings, asset management, brokerage, custody, trustee, legal, regulatory, tax, accounting, investment or valuation advice or services unless a specific service is expressly identified and lawfully provided. Transferability, eligibility, security, true-sale treatment, investor rights and portfolio economics depend on the governing documents, transaction structure, applicable law and qualified professional review.
A practical originate-to-distribute checklist
- Identity: Which exact loan or exposure is being packaged?
- Borrower: Who owes the obligation?
- Current balance: What is outstanding today?
- Terms: Which agreement and amendments are current?
- Performance: Is the asset performing?
- Covenants: Are any breaches or waivers active?
- Collateral: What supports repayment?
- Priority: Where does the claim rank?
- Guarantee: Which support rights exist?
- Transferability: Can the asset be assigned or participated?
- Consent: Whose approval is required?
- Eligibility: Which portfolio rules apply?
- Evidence: What supports each eligibility test?
- As-of date: When was the data last reconciled?
- Portfolio: Which pool contains the asset?
- Membership: When did it enter the pool?
- Substitution: Can it be removed or replaced?
- Servicing: Who continues to manage the borrower relationship?
- Cash flow: Where do payments go after transfer?
- SPV: Which vehicle holds the exposure?
- Tranche: Which securities depend on the asset pool?
- Insurance: Which risk-transfer contracts apply?
- Reporting: Which investor report reflects the current state?
- Provenance: Can every field be traced to a source?
- History: Can the asset still be understood after several portfolio transfers?
If the answer to “can another institution understand this asset without reconstructing the original deal from scratch?” is no, the asset is not operationally portable.
The broader lesson is larger than development finance
The same problem appears in:
- private credit;
- SME loans;
- infrastructure loans;
- mortgage portfolios;
- equipment finance;
- receivables;
- trade finance;
- consumer credit;
- NPL portfolios; and
- other private debt.
Institutional capital can access these markets more easily when the underlying assets have durable identities and comparable current-state data.
Asset classes are built from data continuity
The World Bank’s latest mobilisation numbers are impressive.
But the deeper lesson is structural.
Large pools of capital do not scale by reading one bespoke project file at a time.
They scale when private assets can be:
Identified
Compared
Qualified
Pooled
Transferred
Monitored
without losing their underlying history.
An asset class is not created merely because many similar loans exist. It is created when those loans can be represented consistently enough to move through institutional workflows.
That is why private assets need to become portable before they become scalable.